Research Article | | Peer-Reviewed

An Assessment of the Influence of Forensic Accounting on the Performance of Microfinance Institutions in Mezam

Received: 27 March 2025     Accepted: 7 April 2025     Published: 11 June 2025
Views:       Downloads:
Abstract

The rise in corporate crime and presence of fraudulent activities has led to the collapse of highly reputable MFIs in Cameroon. It is in this light that this current study was aimed at assessing the influence of forensic accounting on the performance of MFIs in Mezam. Two specific research questions and hypothesis were formulated to guide the study. The population of the study was made up of 490 employees of MFIs from which a sample of 220 employees was drawn using Loren’s formula and questionnaires administered. The questionnaires were analyzed using SPSS version 23 and SMART PLS package programs. The Specifically the findings show that a unit increase in the construct forensic audit results to 0.307 units increase in the overall performance of the MFI while a unit increase in the construct forensic litigation results to 0.121 units increase in the performance construct. Also, a unit increase in forensic audit will results to 0.469 units increase in forensic litigations. To conclude from the t-statistics the results revealed that both forensic audit and forensic litigation positively affect performance of MFIs but the effect of forensic litigation was positive and insignificant. At the end it was recommended that MFIs should employ the services forensic accountant on their activities, also they should adopt code of conduct governing the practice of forensic accounting. Last but not the least stake holders, authorities or government should impose the use forensic accounting and auditing in every organisation and other agencies to deter corruption in all sectors of the economy.

Published in Journal of Finance and Accounting (Volume 13, Issue 3)
DOI 10.11648/j.jfa.20251303.12
Page(s) 95-108
Creative Commons

This is an Open Access article, distributed under the terms of the Creative Commons Attribution 4.0 International License (http://creativecommons.org/licenses/by/4.0/), which permits unrestricted use, distribution and reproduction in any medium or format, provided the original work is properly cited.

Copyright

Copyright © The Author(s), 2025. Published by Science Publishing Group

Keywords

Forensic Accounting, Forensic Audit, Forensic Litigation, Performance and Microfinance Institutions

1. Introduction
1.1. Background of the Study
The rise in corporate crime all over the world for the past three decades has made both developing and developed economies to look for possible ways to tackle this cankerworm. Corporate financial accounting scandals no longer become unexpected news of the day. Cases of Enron, World. Com and Global Crossing are among the most prominent companies who have suffered from devastation effects of fraud . These costly scandals have increased global concern on issues of fraud, wiping out billions of dollars of stakeholders’ value and has led to erosion of investors and public confidence in financial markets. The world is trying to be free from the frequent rise in white collar crimes by introducing anti-fraud agencies to cub or fight financial crimes, irregularities and other fraudulent activities in all sectors of the economy .
In addition to the nature of financial fraud and misreporting, it threatens the efficiency of financial markets due to impartial information . The manipulated financial reports to influence shareholders may affect the transparency code of financial markets, it is estimated that $3.5trillons was lost worldwide as a result of fraud in 2011 . The late 1990s witnessed some of the biggest losses incurred by the MFIs in Cameroon. These losses were the result of a range of errors by the MFIs underpricing the risk of the uncollateralised loans they give to the poor and directly competing for customers by opening offices around the country. The Microfinance Institutions MFIs experienced high arrears in loan repayment and bad debts which amounted to around a quarter of the overall total loan portfolio and losses registered in the sector . This situation thus prompted changes in the regulation, supervision, monitoring, control and governance of MFIs in Cameroon. Since then, the microfinance market in Cameroon registered an impressive double-digit growth between the year 2000 to 2010 thanks to expansionary and aggressive marketing penetration strategies adopted by key factors such as Cameroon cooperative Credit Union League CamCCUL, Crédit Communautaire d’AfriqueCCA, Mutuelle Communitaire D’croissance (MC2), . This growth that greeted the microfinance sector in Cameroonslowed as from the early 2011 down due to the collapse of CONFINEST and First Investment Financial Assistance FIFA which greatly affected customers and members perception and confidence towards finance institutions negatively.
In addition, it is very easy to spot out some other microfinance institutions in Cameroonthat opened their doors and closed them three years later, the case of Dominion Finance, Raven Green Finance and Global Finance that went operational between 2008 and 2010 by 2011 they all went bankrupt as a result of fraud, high rates of loan delinquency, poor management of resources and other irregularities. With all these happenings, it further deteriorates the customers confidence and as well as raises doubt on sustainability of microfinance and banking sector in Cameroon . In the same spiral , reiterates the increase of large businesses and the need for corporate governance in Cameroon continuously comes under the spotlight especially after the failures of major companies like the First Investment and Financial Assistance FIFA, CONFINEST, Raven Green finance and others.
1.2. Problem Statement
The absence of truth, fairness, justice and honesty today has resulted to fraud, embezzlement and corruption in the world, Africa and Cameroon to be specific. The presence of fraud and fraudulent activities has become a severe problem across the globe and calls for concern because of its negative consequences on an economy. Fraud is a feature of every organised society in the world and needs to be dealt with properly .
In addition, corporate crimes are very costly, it is estimated that $3.5trillons was lost worldwide as a result of fraud in 2011 . And as such, Cameroon has not been left out of such statistics as one of the most corrupt countries in Africa. The bankruptcy level of Cameroonian companies stands at 32% as per Growth and Development Strategy paper for DSCE. As far as banking and microfinance sector in Cameroon is concern, fraud has manifested itself in different forms as a result of the following reasons; ineffectiveness in the implementation of policies put in place by Central African Banking Commission, poor corporate governance, inadequate technology and weak management information systems, weak internal control and audit mechanisms put in place, non-changing of inefficient board members for long time and the lack of resource to employ forensic accountants.
Furthermore, the management powers to override internal control and audit report for personal gains. The fast-growing nature of MFIs in Cameroon has made their system complex and complicated and hence difficulties of internal control to point out irregularities as well as the non-respect of polices put in place by the Organisation for Harmonisation of Business Law in Africa (OHADA). However the following measures have been put in place to better the management of microfinance institutions in Cameroon, the reinforcement of policies put in place by COBAC and constant supervision, creation of Chartered Institute of Accountants of Cameroon (ONECCA) to audit businesses, powers given to bigger institutions to audit those under their supervision case of Cameroon cooperative Credit Union League (CamCCUL), MC2, the introduction of up to date computer software, such as Delta Bank and improved versions of Alpha software.
In the same light, the implementation of antifraud polices has been reinforced. Also, the dismissal and imprisoning of defrauders with harsh terms has reduced fraud occurrence in MFIs in Cameroon. Despite all these measures put in place, the MFIs has not remained immune from fraud , hence deteriorating customer confidence in the sector, examples include the collapse of First Investment Financial Assistance (FIFA) and CONFINEST and recent BICEC scandal where the director of treasury and accounts disappeared with FCFA 3billion in 2016. As such, there is need for a mechanism to check errors and this has fuelled the growing demand for forensic accounting services . Thusits needs in enhancing the profitability of microfinance institutions in Cameroon cannot be undermined. Although a considerable number of studies have been carried out on the concept of forensic accounting, none of them had focused on assessing the influence of forensic accounting on the performance of microfinance institutions in Cameroon and mezam division to be specific. This leaves a gap that needs to be filled and this work of research is out to fill that gap. It is based on this that the subsequent research questions will be developed to better fill this gap as seen below.
1.3. Research Questions
Main Question
What is influence forensic accounting on the performance of microfinance institutions in Mezam?
Specific Questions
1) Does forensic audit have effect performance of microfinance institutions in Mezam?
2) Does forensic litigation have effect on the performance of microfinance institutions in Mezam?
1.4. Research Objectives
Main Objective
The main objective of this studyis to assess the influence of forensic accounting on the performance of microfinance institutions Mezam.
Specific Objective
1) To investigate the effect of forensic audit on the performance of microfinance institutions in Mezam.
2) To investigate the effect of forensic litigation on the performance of microfinance institutions in Mezam.
1.5. Research Hypothesis
H01: Forensic audithas no significant effect on the performance of microfinance institutions in Mezam.
H02: forensic litigation has no significant effect on the performance of microfinance institutions in Mezam.
1.6. Significance of the Study
To the banking sector Cameroon and microfinance financial institutions to be specific in Bamenda, the study will help top managers and board of directors to incorporate good corporate governance practices to ensure transparency when it comes to financial reporting, as well as put in place anti-fraud policies that will curb fraudulent activities while persecuting its perpetrators and punishing them.
This study forms the basis of research for researchers and academicians on the role of forensic accounting in fraud detection and prevention as well as it effects on the financial performance of microfinance institutions in Cameroon. The study will provide additional empirical literature studies concerning little existing material about fraud in the banking sector and microfinance institutions in Cameroon.
To potential and current investors in Cameroon, the study will provide them with vast information about the importance of the services of forensic accountants on firm’s performance and growth, and as well advice managers on risk related to its exclusion from banking sector and microfinance in particular.
The study will help the government through the ministry of finance to formulate guidelines towards increasing the effectiveness and efficiency of forensic accounting services in reducing the level of fraud microfinance institutions and other sectors in the country.
2. Literature Review
2.1. Conceptual Framework
2.1.1. Forensic Accounting
Forensic accounting refers to the complete or comprehensive view of fraud investigation, it comprises auditing of accounting records to prove or disprove fraud. It also includes preventing fraud and analysing antifraud controls. It is involved in gathering of nonfinancial information such as the interviewing process of all suspected or related parties of fraud and the accumulation of evidence to be presented in the court .
According to forensic science “may be defined as application of the laws of nature to the laws of man”. To him forensic scientists are examiners and interpreters of evidence and facts in legal cases that require expert opinion regarding their finds in court. Forensic accounting comprises forensic litigation and forensic audit. Litigation support provides assistance to matters involving pending or existing litigations. Issues related to quantification of economic damage are handled through litigation while investigative accounting is associated with investigating criminal matters .
2.1.2. Company Performance
According to , performance refers to the ability to operate efficiently, profitability, survive grow and react to the environmental opportunities and threats. In agreement with this, asserts that, performance is measured by how efficient the enterprise is in use of resources in achieving its objectives. It is the measure of attainment achieved by an individual, team, organisation or process. Firms' low performance is the result of poorly performing assets . Low performance from poorly performing assets is often related to strategic errors made in the acquisition process in earlier years.
Measures of Company Performance
Firmsperformance is measured by either subjective or objective criteria, arguments for subjective measures include difficulties with collecting qualitative performance data from small firms and with reliability of such data arising from differences in accounting methods used by firms . He found out that, objective performance measures include indicators such as profit growth, revenue growth. The accounting- based of performance is measured using three indicators: return on assets (ROA), return on equity (ROE), and return on sales (ROS).
2.1.3. Microfinance
Microfinance institutions are institutions that provide financial services to the poor and low-income households in the society allowing them to better manage their risk achieve consistent consumption patterns and develop an economic base . Microfinance Institutions (MFIs) refer to financial institutions which provide financial services to poor economic agents who are typically excluded from the formal banking system for lack of sufficient collateral .
Microfinance is defined as the provision of financial services to low-income economic agents and very poor self-employed and/or unemployed people , Micro finance institutions (MFIs) play a significant role in providing credit to the active but poor and have also greatly contributed to the employment of many people within the economy. In Cameroon, Microfinance is very important, providing credit to most of the rural population. According to the , Cameroon has about 7.3 million living below the national poverty line.
2.2. Theoretical Framework
2.2.1. The Agency Theory
This theory explains the relationship between principal (shareholders) and agents (employees) of a company’s that is aim at achieving objectives of the business. define an agency relationship as a “contract under which one or more persons (the principal(s) engage another person (the agent) to perform some service on their behalf which involves delegating some decision-making authority to the agent. Agency theory describes firms as necessary structures to maintain contracts, and through firms, it is possible to exercise control which minimizes opportunistic behaviour of agents.
Accordingly, it posits that in order to harmonize the interests of the agent and the principal, a comprehensive contract is written to address the interest of both the agent and the principal. This theory further explains that the relationship is strengthened by the principal employing an expert to monitor the activities of agents. This point of view supported by who maintains that the contract provides for conflict resolution between the agent and principal, the principal determines the work and agent undertakes the work. He however, proposes that the principal suffers shirking which deprives him or her from benefiting from the work of the agent.
Nevertheless, the theory recognises the incomplete information about the relationship, interests or work performance of the agent described as adverse selection and moral hazard. explains that moral hazard and adverse selection affects the output of the agent in two ways; not doing exactly what the agent is appointed to do, and not possessing the requisite knowledge about what should be done. This therefore, affects the overall performance of the relationship as well as the benefits of the principal in form of cash residual.
2.2.2. Fraud Triangle Theory by Donald Cressey (1953)
The fraud triangle originated from Donald Cressey's hypothesis: “Trusted persons become trust violators when they conceive of themselves as having a financial problem which is non-shareable, are aware this problem can be secretly resolved by violation of the position of financial trust, and are able to apply to their own conduct in that situation verbalizations which enable them to adjust their conceptions of themselves as trusted persons with their conceptions of themselves as users of the entrusted funds or property” .
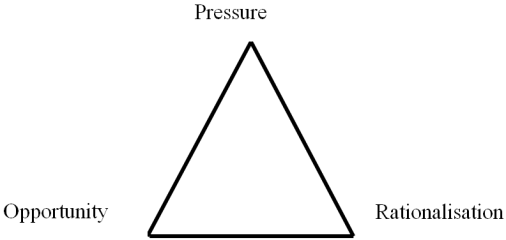
This theory was first coined by Cressey in 1953. Fraud triangle theory identifies that lead culprits to commit fraud. Fraud triangle describes three major factors that are present in any fraud situation: (a) perceived pressure, (b) opportunity, and (c) rationalisation. The elements are explained below under each heading.
Figure 1. Fraud Triangle.
Perceived pressure
Perceived pressure for committing fraud in financial institutions in case can be likened to the motivation, that is what pushes one to commit fraud. These pressures can either be financial or non-financial pressures . Pressure sometimes involves personal situations that create a demand for more money; such situations might include vices like drug use or gambling or merely life events like a spouse losing a job, Addictions such as gambling and drugs may also motivate someone to commit fraud .
Opportunity
The Opportunity to commit fraud is possible when employees have access to assets, information that allows them to both commit and conceal fraud. Employees are given access to records and valuables in the ordinary course of their jobs. Unfortunately, that access allows people to commit fraud, “opportunity” can be seen as the ability to override the internal control and check systems put in place . Failure to establish adequate procedures to detect fraudulent activity also increases the opportunities fraud for to occur.
Rationalisation
Rationalisation involves a person reconciling his/her behaviour with the commonly accepted notions of decency and trust. There are two aspects to rationalisation: firstly the fraudster must conclude that the benefits to be realised from a fraudulent activity outweigh the possibility for detection, Secondly that the fraudster needs to justify the fraud. Justification can be related to job dissatisfaction or perceived entitlement, or a current intent to make the victim whole sometime in the future, or saving one’s family, possessions or status.
2.2.3. The Fraud Diamond Theory
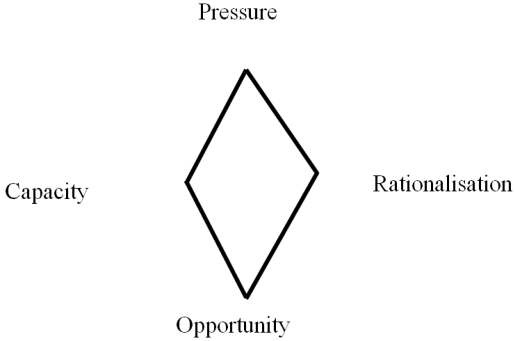
The fraud diamond theory was first presented by in a journal. It is viewed as an expanded version of the fraud triangle theory. In this expanded version of the, an element of capacity was added to the initial three fraud components fraud triangle theory. , argued that although perceived pressure might coexist with opportunity and rationalisation, it is unlikely for u fraud to take place unless the fourth element (capability) is present. In other words, potential perpetrators must have the skills and ability to be able to commit fraud.
Capability refers to a situation when employees have the necessary traits or skills and ability to commit fraud. In this situation the fraud perpetrator uses opportunity and skills and turns his objectives to reality . This element that differentiates fra1ud triangle from the fraud diamond theory as seen bellow.
Source: Wolfe and Hermanson (2025)

Download: Download full-size image

Figure 2. Fraud Diamond Theory.
2.2.4. Label Theory of Crime
This theory was brought forth by Honard Becker in 1963. This theory sees criminal behavior as being defined by society. This theory holds that deviant behavior is not inherent to an act but instead focuses on the tendency of majorities to negatively label the minority or the few of those seen as deviant from standard cultural norms . Deviance is not a quality of acts a person commits but rather a consequence of the application by other rules sanction to a defender. The theory does not deal with questions like why people become criminals but instead tells us why society label some individual as criminal or deviants.
This theory is pegged on the following assumptions; no act is intrinsically criminal, statistically research can be relied on to be accurate, deviants are different from normal people. More criminal are committed and individual forms an identity that criminal along with all associates, attitudes and believes in the process of deviants .
2.3. Empirical Framework
According to explored the impacts of forensic accounting on the financial performance of investment firms in Nigeria. Using five- year-old studies, the research revealed that the growth of technology had influenced the emergence of accounting frauds such as money laundering, assets misappropriation, bribery, corruption, and manipulation of accounting records among others. He realised that forensic accounting combines investigations, litigation, auditing, and financial reporting skills to detect and prevent frauds. Similarly, it promotes corporate governance, mitigation of accounting irregularities, quality financial reporting practices, improved internal control, and shareholders’ trust. On these bases he concluded that, forensic accounting promotes the performance and profitability of investment firms.
According to , forensic accounting has a significant positive pillar to gaining the trust and confidence of investors in the market. Integrity of financial statements is associated to accuracy quality and transparency in recording and reporting all business transactions and as well internal control process. Despite lack of guarantee or assurance, integrity in financial reporting may be translated into higher investment or performance in terms of profitability. the absence forensic accounting uncovered, unveiled. The results of the study revealed that nearly about 23% of the integrity of financial statements is attributed to forensic accounting techniques and tools. Hence the conclusion that forensic accounting techniques and tools improve the efficiency of internal controls systems which translate into the overall productivity of the organisation and profitability.
In addition , forensic accounting has a significant positive pillar to gaining the trust and confidence of investors in the market. Integrity of financial statements is associated to accuracy quality and transparency in recording and reporting all business transactions and as well internal control process. Despite lack of guarantee or assurance, integrity in financial reporting may be translated into higher investment or performance in terms of profitability. the absence forensic accounting uncovered, unveiled. The results of the study revealed that nearly about 23% of the integrity of financial statements is attributed to forensic accounting techniques and tools. Hence the conclusion that forensic accounting techniques and tools improve the efficiency of internal controls systems which translate into the overall productivity of the organisation and profitability.
Furthermore, in spiral , research focused on forensic accounting in Nigerian university financial systems and made use the ex-post facto research design with descriptive and inferential statistics while making use of financial and accounting data from 2004 to 2014. The study’s results revealed that financial management requires the use of forensic accounting to oversee the processes and ensure transparency in financial reporting. further , reiterated that skilled forensic accountant working with relevant technology would not only enhance efficiency in financial management and reporting but also help prevent irregularities and misconduct in the firm.
Again, , revealed that forensic accounting enables firms to continually inspect the financial statements, detection of all intended or unintended frauds. The team studied the use of forensic accounting on corporate crime mitigation through statistical analysis of data collected from the Economic and Financial Crimes Commission, KPMG, Deloitte, and PwC subsidiaries in Nigeria. The study revealed that 56.1% of the participants consider forensic accounting could complement auditing to mitigate corporate crimes facing Nigerian investment firms. The findings further revealed that 66.7% of participants agreed that corporate crime mitigation strengthens corporate governance which is the primary pillar for improved business performance and profitability.
Also , targeted a population comprised of all 609 forensic managers, their staff and internal control managers and their staff. For purpose of his study, a sampling frame of 21 commercial banks was taken. The findings indicated that forensic investigation and forensic litigation was statistically significant in explaining changes in financial performance of commercial banks with evidence from the mean score of 3.984 indicating that majority of respondents agreed that forensic investigation and forensic litigation influence financial performance. The study concluded from its findings that forensic investigation and forensic litigation were statistically significant according to the R square of 42.9%. Explaining that 42.9% of the changes in financial performance of commercial banks in Nigeria.
In addition, , in his research paper used descriptive research survey design and a sample of 47 respondents in 16 commercial banks in Kenya. The data was analyzed using Statistical package for social sciences (SPSS). The study findings indicated that the application of forensic accounting services by banks led to increased fraud prevention in the commercial banks and the highest application was on enhancing quality of financial reporting this help in improving financial performance of banks. The most prevalent type of fraud in the banking sector was fraudulent expense claims. The study revealed that fraud investigation impacts on fraud prevention by an organization through review of financial reports, performing electronic evidence discovery, fraud risk assessment, examination of financial and source documents, looking into alleged fraud or illegal activity, structure regulatory compliance strategies and probe suspect financial performance.
Again, , employed Chi- square and statistics package for social science to empirically evaluate forensic accounting as an antidote to economic and financial crime in Nigeria. In their collective efforts four hypothesis were designed and tested. The study revealed that forensic accounting is a financial strategy to curb and resolve economic and financial crimes in Nigerian economy.
Last but not the least, , examined the effect of forensic accounting services in fraud detection. The primary data was collected with the help of a well-structured questionnaire of three sections administered to twenty-four banks in Port Harcourt, the capital of Rivers State and the data collected from the questionnaires were analyzed with descriptive statistics, Augmented Dickey-fuller, ordinary least square and Granger Causality. The result reveals that the application of forensic accounting services affects the level of fraudulent activities of banks.
3. Methodology
3.1. Scope and Area of Study
The researcher used a period of 8months to assess the influence of forensic accounting on the performance of microfinance institutions within the North West Region of Cameroon. The study was limited to category onemicrofinance institutions those affiliated to CamCCUL, RECCU-CAM Ltd and other, found within Mezam Division of the North West Region of Cameroon. The study focused on managers, accountants, controllers and forensic accountants and auditors of these institutions.
3.2. Research Design
The study used cross sectional research design of all the microfinance institutions in the northwest region to be precise those of Mezam Division belonging to network of CamCCUL, RECCU-CAM, and others.
3.3. Population and Sample of the Study
The population of the study comprises of about 490 staffs of accounting/finance, internal audit and control departments of all the credit unions in Mezam Division of the northwest region of Cameroon affiliated to CamCCUL Ltd and RECCU-CAM. A sample of 220 employees was selected from the total population of about 490 employees incredit unions found within in the Mezam division of the northwest region of Cameroon; this was done with the use of Loren’s formula which gives the researcher the opportunity selects a sample which can be easy to meet and administer questionnaires rather than using the whole population. In addition, study used probability sampling technique for the selection sample used. To beprecise the simple random sampling technique was adopted. This is justified by the fact that during the research all credit unions within Mezam had equal chances of being selected.
3.4. Model Specification
3.4.1. Functional Form of the Model
The model below is based on the assumptions that the financial performance of microfinance institutions is a function of forensic investigation, forensic audit and forensic litigation. The study assumes a direct relationship forensic accounting and performance of microfinance institutions in Cameroon.
Performance=f(forensicaccounting)
Splitting up forensic accounting into the different specific components gives the following functional model
Performance=f(forensicaudit,forensiclitigation).
For easy understanding it is simplified into;
P=f(FA,FL)
FA: Forensic Audit
FL: Forensic Litigation
3.4.2. Empirical Form of the Model
The transformation of the functional model into a mathematical model gives it a better explanation of forensic accounting as the independent variable subdivided into forensic investigation, forensic audit and litigation to have influence on financial performance of microfinance institutions and taking into consideration the stochastic term or error term.
However, the other variables that also affect performance of microfinance institutions are: Savings level, Loan portfolio, Interest rate variation and corporate governance have been incorporated into the model as control variable to be able to capture all aspects of financial performance.
Y=B0+B1FA+B2FL+e
Y: Performance is a latent construct (unobserved) captured through a cluster of manifests (reflexive measures) which are returns on assets, self-sufficiency, membership, meeting of objective and number of branches. This is preferred over using a single measure because it is multifaceted.
FA: Forensic audit
FL: Forensic litigation
B0: Constant of the model
B1 and B2are parameters of the model
e: error term or stochastic error.
4. Results and Discussion of Finding
Table 1. Response Rate.

Number of questionnaires

Number

Percentage

Questionnaires returned

200

90.9%

Questionnaires not returned

20

9.1%

Total

220

100%

Source: Field Survey Results, (2025)
The effect of Forensic Audit and Forensic Litigation on Performance of MFIs
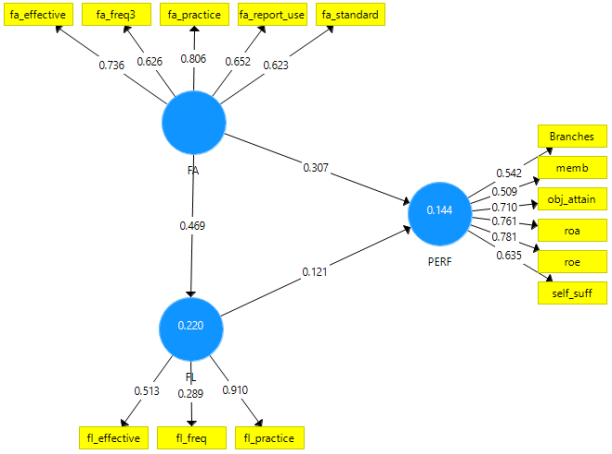
The structural equation model was used and after running the PLS algorithm the following Structural Equation Model was obtained.
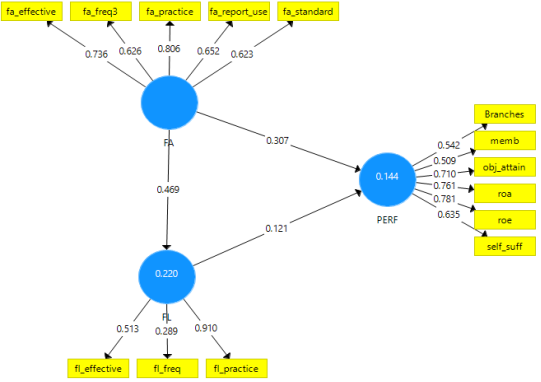
Figure 3. Structural Equation Model Results for the Various Latent Constructs.
The PLS Algorithm results presented on figure 3 above show the outer factor loadings, path coefficients and the R-Square of the latent constructs. The results illustrates that, the construct forensic audit is explained more by forensic audit practice, forensic audit effectiveness and forensic audit report use with higher factor loadings of 0.806, 0.736 and 0.652 respectively. Forensic audit frequency and forensic audit standards have lower factor loadings of 0.626 and 0.623 respectively.
Also, the construct forensic litigation is explained more by forensic litigation practice and forensic litigation effectiveness with higher factor loadings of 0.910 and 0.513 respectively. Forensic litigation frequencies also have lower factor loadings of 0.289. The findings show that 22.0 percent of variations in the construct forensic litigation are explained forensic audit construct.
The results also illustrates that, the construct performance of MFIs is explained more by return on equity (ROE), return on assets (ROA) and objectives attainment with outer loadings of 0.781, 0.761 and 0.710 respectively while lower loadings were observed for membership, number of branches and self-sufficiency. This means that financial performance measures explain overall performance of MFIs more than the operational performance measures. The findings also reveal that 14.4% of variations on performance of MFIs are explained by forensic audits and forensic litigations.
The path coefficients show that both forensic audit and forensic litigations positively affect the performance of MFIs while forensic audit also positively induces forensic litigations. The findings specifically shows that a unit increase in the construct forensic audit results to 0.307 units increase in the overall performance of the MFI while a unit increase in the construct forensic litigation results to 0.121 units increase in the performance construct. Also, a unit increase in forensic audit will results to 0.469 units increase in forensic litigations.
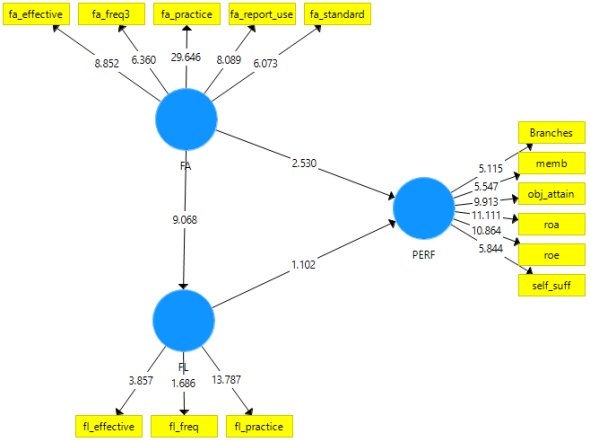
The above results however give just the path coefficients which show the effect size of each of the determinants but does not give any information about the significance of the effects. The significance of the effects was assessed by the bootstrapping results that present the t-statistics of the effects which helps in testing the hypotheses of the study. Figure 2 presents the t-statistics of the effects and the results presented in figures 3 and 4 are summarised in table below.
Figure 4. Bootstrapping for the Various Latent Constructs.
SmartPLS provides “t” statistics to test the significance of the inner and outer models, using a procedure called bootstrapping. In this process, a large number of subsamples are produced based on the original sample, with replacement, to obtain the standard bootstrap errors, which in turn permit the approximate estimation of “t” values for significance tests of the structural paths . The theoretical relation (path) forecasted between all constructs is statistically significant at 5% level of significance if the predicted t-statistics is greater than 1.96 critical t-statistics. The t-statistics presented in figure 4 which are used in testing the hypothesis of the study are presented in table 2 below;
Table 2. Path Coefficients, Mean, STDEV, T-Values, P-Values.

Original Sample (O)

Sample Mean (M)

Standard Deviation (STDEV)

T Statistics (|O/STDEV|)

P Values

FA -> FL

0.469

0.482

0.052

9.068

0.000

FA -> PERF

0.307

0.311

0.121

2.530

0.012

FL -> PERF

0.121

0.145

0.110

1.102

0.271

Source: Author
The findings in table 2 above present a summary of the results that are used in testing the hypothesis of the study. The Different null hypotheses stated in the study are:
Hypothesis Null One: Forensic Audit has not significantly affect on the performance of MFIs in Mezam.
From the results the coefficient of 0.307 again reveals that forensic audit positively affect the performance of MFIs and the t-statistics of 2.530 reveals that the effect of forensic audit on performance is significant at 5% level of significance as the t-statistics is by far greater than the 1.96 critical t-statistics at 5% level and this is also reflected by the p value being less than 0.05. Thus, we reject the first null hypothesis and conclude that forensic audit positively and significantly affects the performance of MFIs in Mezam.
Hypothesis Null Two: Forensic Litigation has no significantly effect on the performance of MFIs in Mezam.
From the results the coefficient of 0.121 again reveals that forensic litigation positively affect the performance of MFIs and the t-statistics of 1.102 reveals that the effect of forensic litigation on performance is insignificant as the t-statistics is less than the 1.96 critical t-statistics at 5% level and this is also reflected by the p value being greater than 0.05. Thus, we accept the second null hypothesis and conclude that forensic litigation positively but insignificantly affects the performance of MFIs in Mezam.
Other finding worthy of note is the fact that forensic audit positively induces forensic litigations and the effect of forensic audit on forensic litigation reflected by the t-statistics of 9.068 is significant at 5% level of significance by the same analogy.
Table 3. Outer Loadings, Mean, STDEV, T-Values, P-Values.

Original Sample (O)

Sample Mean (M)

Standard Deviation (STDEV)

T Statistics (|O/STDEV|)

P Values

Branches <- PERF

0.542

0.529

0.106

5.115

0.000

FAeffective<- FA

0.736

0.718

0.083

8.852

0.000

FA freq3 <- FA

0.626

0.608

0.098

6.360

0.000

FA practice<- FA

0.806

0.809

0.027

29.646

0.000

FA report use<- FA

0.652

0.658

0.081

8.089

0.000

FA standard<- FA

0.623

0.601

0.103

6.073

0.000

FL effective<- FL

0.513

0.543

0.133

3.857

0.000

FL freq<- FL

0.289

0.293

0.172

1.686

0.092

FL practice<- FL

0.910

0.880

0.066

13.787

0.000

Memb<- PERF

0.509

0.516

0.092

5.547

0.000

Obj_attain<- PERF

0.710

0.697

0.072

9.913

0.000

ROA<- PERF

0.761

0.747

0.068

11.111

0.000

ROE<- PERF

0.781

0.764

0.072

10.864

0.000

Self suff<- PERF

0.635

0.624

0.109

5.844

0.000

Source: Author (2025)
The T statistics show the outer model are all highly significant at the 5% level of significance given the fact that the all the T statistics are all greater than 1.96.
Blindfolding test results of predictive relevance follows thus.
Figure 5. Structural Equation Model Results for the Various Latent Constructs.
Discussion of Findings
The study reveals that forensic audit/investigations have a positive and significant effect on the performance of microfinance institutions with Mezam division of the northwest region of Cameroon. The coefficient of 0.307 from the findings reveals that forensic audit positively affect the performance of MFIs and the t-statistics of 2.530 reveals that the effect of forensic audit on performance is significant at 5% level of significance as the t-statistics is by far greater than the 1.96 critical t-statistics at 5% level and this is also reflected by the p value being less than 0.05. Thus, we reject the first null hypothesis and conclude that forensic audit positively and significantly affects the performance of MFIs in Mezam. This is in line with the findings of other researchers like , who explored the impacts of forensic accounting on the financial performance of investment firms in Nigeria and the effect of forensic accounting on the performance of commercial banks in Nigeria respectively. In the same spiral a construct coefficient of 0.307>0, reveals that the effect of forensic audit on performance of MFIs which is in agreement with the apriori expectations of the study which indicated B1>0.
In addition, the results of the study also revealed that the practice of forensic audit is vital in MFIs as it plays an important role in the detection and prevention of fraud. The results further indicated that the practice of forensic audit activities is in line with respect to international standards put in place to govern the profession, thus ensuring integrity of financial statements of MFIs with Mezam which is the heart of the sector in the northwest region and Cameroon in general. These Findings were in line with the works of researchers such as . The results are also in agreement with the theoretical expectations of Agency Theory which is based on the assumption that, for agency conflict to be well handled in an organisation there is a need for Mechanism to check the activities of principal (shareholders) as well the agent (employees) and in this case the forensic accounting service plays that role.
Furthermore, the findings of the study indicates that forensic litigation positively affects performance of Microfinance institutions but the effect on performance is insignificant these findings tie with the earlier stated apriori expectations B2>0 as seen on the construct coefficient of 0.121>0 generated from the algorithm showing forensic litigation positively affects performance, these findings are in agreement with works of other researchers such as the . This is because forensic litigation provides assistance of all nature to issues related to existing or pending litigation. Thus, forensic accountant are there to testify as expert witness with evidence when issues concerning fraud are addressed in the courtroom.
5. Conclusions and Recommendation
5.1. Conclusion
Based on the finding above, the research concludes that MFIs practicing forensic accounting will help detect and prevent the occurrence of fraud. As revealed by the study, forensic accounting is seen as a supplementary tool in fraud detection and prevention in MFIs; which goes a long way to improve the overall performance of MFIs. The study further reveals that the practice of forensic accounting in respect to international standards will promotes transparency, accountability and good corporate governance at all levels of organisation.
In addition, the results from the constructs reveals that forensic audit is explained more by forensic audit practice, forensic audit effectiveness and forensic audit report use with higher factor loadings of 0.806, 0.736 and 0.652 respectively. Forensic audit frequency and forensic audit standards have lower factor loadings of 0.626 and 0.623 respectively.
In the same spiral, from the construct forensic litigations is explained more by forensic litigation practice and forensic litigation effectiveness with higher factor loadings of 0.910 and 0.513 respectively. Forensic litigation frequencies also have lower factor loadings of 0.289. The findings show that 22.0 percentages of variations in the construct forensic litigation is explained forensic audit construct.
The results also illustrate that, the construct performance of MFIs is explained more by return on equity (ROE), return on assets (ROA) and objectives attainment with outer loadings of 0.781, 0.761 and 0.710 respectively while lower loadings were observed for membership, number of branches and self-sufficiency. This means that financial performance measures explain overall performance of MFIs more than the operational performance measures. The findings also reveal that 14.4% of variations on performance of MFIs are explained by forensic audits and forensic litigations.
To conclude on the bases on the path coefficients, both forensic audit and forensic litigations positively affect the performance of MFIs. Although the effect of litigation on performance was insignificant, forensic audit also positively induces forensic litigations and this is a call for concern for all stakeholder involved to ensure better performance of microfinance institutions in mezam and why not Cameroon in general.
5.2. Recommendations
Based on the findings of this work of research, the following recommendations were made.
First of all, the entire banking sector in Cameroon and MFIs to be specific, needs an independent, accountability, detection and protection legal supervisor (forensic accounting services). This is because the traditional audit has limitation of detecting fraudulent practices beyond the books of accounts and software put in place as such forensic accounting services will eventually fill this gap. It is important to note that forensic accountants have the professional ability backed up by law to break into organizational systems, examine books, software to make discoveries and present evidence in court when the interest of stakeholders of the institution is at stake. In the same light forensic accounting will go a long way to promote transparency and good governance, while restoring the confidence of the low in class of person to believe they can benefit with full confidence the services MFIs offer.
Furthermore, organisations should try by all possible means to adopt professional code of conduct and guidelines for the practice of forensic accounting and investigation to be able to check all act of fraud and punish its perpetrators. In the same lights employees of MFIs should not be allowed to occupy a particular duty post for a long period of time, this is because it can lead concealing of fraudulent activities without easily been noticed which is a common in credit unions.
Also, the study recommended that stake holders, authorities or government should impose the use forensic accounting and auditing in everyorganisation and other agencies to deter corruption in all sectors of the economy. This is because the image of Cameroon has been tarnished at the international community thereby discouraging foreign direct investment as a result of economy and financial crimes. This has effect on development, employment and the standard of living of the people. Eradication of economic and financial crime through the adoption of forensic accounting in the system will improve the image of companies in Cameroon.
A Curriculum should be developed by tertiary institutions in Cameroon offering accountancy and accounting education to ensure that forensic accounting and investigation are offered from the undergraduate level in their institutions not just the post graduate level to ensure that adequate attention is paid to this special area of accounting which is fast gaining grounds in Cameroon. Higher institutions of learning in Cameroon can also partner with Foreign Forensic accounting certification institutes abroad such as the International Institute of Certified Forensic Investigation Professionals USA, INC. (ICFIP) to train and certify professionals in Cameroon while reducing the cost of travelling abroad to study forensic accounting.
Training programs, seminars and conferences should be organized in the areas of forensic audit/investigation, forensic litigation to help accountants and other employees of companies to be able to acquire basic forensic accounting skill and how to handle forensic litigations issues. The 7th IICFIP Global Forensic Conference was to be held in Cameroon from the 22 to the 24th of June postponed to November with its “New Perspectives in Cyber Terrorism, Counter Insurgency, Financial Intelligence and Forensic Investigation” but unfortunately due to the corona virus pandemic it has been shifted to the mid-2021.
5.3. Limitations of the Study
In the course of carrying out this research the researcher encountered allot of shortcomings which include the following, the Anglophone crisis which made movement difficult for the administration of questionnaires in some parts of Mezam division as separatist fighter from time-to-time imposed ghost town days that rendered microfinance institutions non-functional for weeks due to insecurity. This explains why 9.1% of the questionnaires administered to MFIs were not returned.
In addition, the COVID 19 pandemic also made things difficult for the research to be able to collect sensitive information from interviewing some of the managers, accountants and internal controllers as a two months complete lockdown throughout the national territory. This further brought fear in society as people could not normally interact as before and this explains a turnout of 9.1% of questionnaire that were not returned.
This study also had a limitation in terms of the scope and area of study because it only concentrated on the category oneMFIs (credit unions) and ignored other category two microfinance institutions. This may limit fair findings that could have been gotten if a bigger number of observations could have been to carry out the analysis.
Abbreviations

SPSS

Statistical Package For Social Sciences

CamCCUL

Cameroon Cooperative Credit Union League

RECCU-CAM

Renaissance Cooperative Credit Unions in Cameroon

OHADA

Organisation for Harmonisation of Business Law in Africa

MC2

Mutuelle Communitaire D’croissance

FIFA

First Investment Financial Assistance

MFI

Micro Finance Institutions

FA

Forensic Audit

FL

Forensic Litigation

ROA

Return On Assets

ROE

Return On Equity

ROS

Return On Sales

Declaration
Originality and Copyright Declaration
Original work, not published elsewhere, author retains copyright.
Ethics and Data Protection Declaration
Research conducted ethically, data anonymized, confidentiality maintained.
Author Contributions
Ngong Derick Ngum is the sole author. The author read and approved the final manuscript.
Conflicts of Interest
The author declares no conflicts of interest.
References
[1] Abiola, I., & Oyewole, A. T. (2013). Internal control system on fraud detection: Nigeria experience. Journal of Accounting and Finance, 13(5), 141-152.
[2] Adams, M. B. (1994). Agency theory and the internal audit. Managerial auditing journal.
[3] Agbaje, O. (2012). Corruption in Nigeria. Businessday Online. Wednesday, 9.
[4] Akindele, R. I. (2011). Fraud as a negative catalyst in the Nigerian banking industry. Journal of Emerging Trends in Economics and Management Sciences, 2(5), 357-383.
[5] Akintoye, I. R. (2008). The basics of environmental and forensic Accounting. Lagos: Unique Educational Publishers.
[6] Allen, R. D., Hermanson, D. R., Kozloski, T. M., & Ramsay, R. J. (2006). Auditor risk assessment: Insights from the academic literature. Accounting Horizons, 20(2), 157-177.
[7] Amiram, D., Bozanic, Z., Cox, J. D., Dupont, Q., Karpoff, J. M., & Sloan, R. (2018). Financial reporting fraud and other forms of misconduct: a multidisciplinary review of the literature. Review of Accounting Studies, 23(2), 732-783.
[8] Athanasoglou, P. P., Brissimis, S. N., & Delis, M. D. (2008). Bank-specific, industry-specific and macroeconomic determinants of bank profitability. Journal of international financial Markets, Institutions and Money, 18(2), 121-136.
[9] Baron, L. (2006). CPAs are a hot commodity. Journal of Accountancy, 201(2), 16.
[10] Becker, H. S. (2008). Tricks of the trade: How to think about your research while you're doing it. University of Chicago press.
[11] Bradford, M., Earp, J. B., Showalter, D. S., & Williams, P. F. (2017). Corporate sustainability reporting and stakeholder concerns: Is there a disconnect?. Accounting Horizons, 31(1), 83-102.
[12] Caponera, D. A., & Nanni, M. (1992). Principles of Water Law and Administration: National and International 2nd edition, revised and updated by Marcella Nanni. CRC Press.
[13] Cronbach, L. J. (1951). Coefficient alpha and the internal structure of tests. psychometrika, 16(3), 297-334.
[14] Dada, S. O., Enyi, P. E., & Owolabi, S. A. (2013). Forensic accounting: A relevant tool for effective investigation of bribery cases in Nigeria. Unique Journal of Business Management Research, 1(5), 095-099.
[15] Ebimobowei, O. A. C., & Onuorah, A. (2011). Fraudulent Activities and Forensic Accounting services of Banks Port Harcout, Nigeria. Asian Journal of Business Management, 4(2), 124-129.
[16] Eccles, J. S., & Harold, R. D. (1991). Gender differences in sport involvement: Applying the Eccles' expectancy-value model. Journal of applied sport psychology, 3(1), 7-35.
[17] Elle, S. M. (2012). Microfinance and entrepreneurship in Cameroon. Table of Content Volume VIII, Issue 1, May 2012.
[18] Emmanuel, O. G., Enyi, E. P., & Olajide, D. S. (2018). Forensic accounting techniques and integrity of financial statements: an investigative approach. Journal of African Interdisciplinary Studies (JAIS), 2, 3.
[19] Enofe, A. O., Okpako, P. O., & Atube, E. N. (2013). The impact of forensic accounting on fraud detection. European Journal of Business and management, 5(26), 61-72.
[20] Fadipe-Joseph, O. A., & Titiloye, E. O. (2012). Application of continued fractions in controlling bank fraud. International Journal of Business and Social Science, 3(9), 210-213.
[21] Farrell, B. R., & Franco, J. R. (1999). The role of the auditor in the prevention and detection of business fraud: SAS No. 82. Western Criminology Review, 2(1), 1-12.
[22] Feyitimi, O., Temitope, O. A., Akeem, L. B., & Samuel, O. (2016). Tax Incentives and the Growth of Small and Medium Scale Enterprises in Developing Economy–The Nigerian Experience. European Journal of Research and Reflection in Management Sciences Vol, 4(2).
[23] Fornell, C., & Larcker, D. F. (1981). Structural equation models with unobservable variables and measurement error: Algebra and statistics.
[24] Fotabong, L. A. (2012). The Microfinance Market of Cameroon-Analyzing Trends and Current Development. Available at SSRN 2007912.
[25] Haenlein, M., & Kaplan, A. M. (2004). A beginner's guide to partial least squares analysis. Understanding statistics, 3(4), 283-297.
[26] Halling, M., & Hayden, E. (2006). Bank failure prediction: a two-step survival time approach. Available at SSRN 904255.
[27] Holmström, B., & Tirole, J. (1998). Private and public supply of liquidity. Journal of political Economy, 106(1), 1-40.
[28] Holmström, B., & Tirole, J. (2000). Liquidity and risk management. Journal of Money, Credit and Banking, 295-319.
[29] Huber, W. (2012). Is forensic accounting in the United States becoming a profession?. Journal of Forensic & Investigative Accounting, 4(1).
[30] International Monetary Fund (2018) Microfinance Linkages in Cameroon. Selected Issues Paper. IMF Country report No 18/256. Washington IMF.
[31] Jensen, M. C., & Meckling, W. H. (1976). Theory of the firm: Managerial behavior, agency costs and ownership structure. Journal of financial economics, 3(4), 305-360.
[32] Jensen, M., & RUBACK, R. (1986). Market for Corporate Control, AEA Papers and Proceedings, Vol, 76.
[33] Kenyon, W., & Tilton, P. D. (2012). Potential red flags and fraud detection techniques. A guide to forensic accounting investigation, 231-269.
[34] Koh, A. N., Arokiasamy, L., & Suat, C. L. A. (2009). Forensic accounting: Public acceptance towards occurrence of fraud detection. International Journal of Business and Management, 4(11), 145-149.
[35] Kothari, C. R. (2004). Research methodology: Methods and techniques. New Age International.
[36] Kotler, P. (1997). Marketing management: Analysis, planning, implementation and control.
[37] Krambia-Kapardis, M. (2002). A fraud detection model: A must for auditors. Journal of Financial Regulation and Compliance, 10(3), 266-278.
[38] Mansor, N. (2015). Concomitant debacle of fraud incidences in the Nigeria public sector: Understanding the power of fraud triangle theory. International journal of academic research in business and social sciences, 5(9), 2222-6990.
[39] Manurung, D. T., & Hadian, N. (2013, November). Detection fraud of financial statement with fraud triangle. 23rd International Business Research Conference, World Business Institute.
[40] Minchella, D. J., Sollenberger, K. M., & De Souza, C. P. (1995). Distribution of schistosome genetic diversity within molluscan intermediate hosts. Parasitology, 111(2), 217-220.
[41] Morduch, J. (1999). The microfinance promise. Journal of economic literature, 37(4), 1569-1614.
[42] Mugenda, O. M., & Mugenda, A. G. (1999). Research methods: Quantitative and qualitative approaches. Acts press.
[43] Mukoro, D. O., Faboyede, O. S., & Yamusa, O. (2006). Forensic Accounting and Fraud management Perspective. An Integrated Approach.
[44] Murdoch, J., Marsden, T., & Banks, J. (2000). Quality, nature, and embeddedness: Some theoretical considerations in the context of the food sector. Economic geography, 76(2), 107-125.
[45] Niba, A. N. (2016). Internal Controls, and the Incidence of Fraud in Microfinance Inststutions in the Southwest Region of Cameroon.
[46] Nwaiwu, J. N., & Aaron, F. C. (2018). Forensic accounting relevance and fraud detection process and financial performance in Nigeria. International Journal of Advanced Academic Research Accounting and Economic Development, 4(2), 16-35.
[47] Nwaze, C. (2006). Bank fraud exposed with cases and preventive measures. Control and Survellance Associates Limited.
[48] Nwaze, C. (2011). Fraud and anti-fraud challenges in contemporary Nigerian banking. Zenith Economic quarterly.
[49] Nyakundi, D. O., Nyamita, M. O., & Tinega, T. M. (2014). Effect of internal control systems on financial performance of small and medium scale business enterprises in Kisumu City, Kenya. International Journal of Social Sciences and Entrepreneurship, 1(11), 719-734.
[50] OGOUN, S., & ADUMEIN, G. W. Towards Exchange Rate And Financial Deepening: A Dependency Determination.
[51] Ogunleye, G. A. (2005, February). Regulatory challenges in a consolidated Nigerian banking system-NDIC perspective. In The 14th Delegates Conference/Annual General Meeting of the Money Markets Association of Nigeria, Lagos (Vol. 24).
[52] Omondi, E. O. (2013). The impact of forensic accounting services on fraud detection and prevention among Commercial Banks in Kenya (Doctoral dissertation, University of Nairobi).
[53] Omri, A., Ghorbel, F., & Baklouti, F. (2009). Impact of the external audit on the quality of the accounting result: Case of listed Tunisian companies. Governance review, 6 (2).
[54] Osho, A. E. (2017). Impact of forensic accounting on university financial system in Nigeria. European Scientific Journal, 13(31), 571-590.
[55] Oyedokun, G. E. (2013). Audit, investigation and forensic accounting: Similarities and differences. Being a lecture delivered at the Institute of Chartered Accountants of Nigeria’s forensic accounting certification programme.
[56] Popoola, O. M. J., Che-Ahmad, A., & Samsudin, R. S. (2013, April). Forensic accounting knowledge and skills on task performance fraud risk assessment: Nigerian public sector experience. In Proceedings of the Global Symposium on Social Sciences (IBSSS, 2013), Okinawa, Japan.
[57] Popoola, O. M. J., Che-Ahmad, A., & Samsudin, R. S. (2014). Forensic accounting and fraud: capability and competence requirements in Malaysia. Journal of Modern Accounting & Auditing, 10(8), 825-834.
[58] Ramaswany, V., & Grouillart, F. (2011). L'entreprise co< réative. Paris, Vuibert.
[59] Ringle, C. M., Wende, S., & Will, A. (2010). Finite mixture partial least squares analysis: Methodology and numerical examples. In Handbook of partial least squares (pp. 195-218). Springer, Berlin, Heidelberg.
Cite This Article
  • APA Style

    Ngum, N. D. (2025). An Assessment of the Influence of Forensic Accounting on the Performance of Microfinance Institutions in Mezam. Journal of Finance and Accounting, 13(3), 95-108. https://doi.org/10.11648/j.jfa.20251303.12

    Copy | Download

    ACS Style

    Ngum, N. D. An Assessment of the Influence of Forensic Accounting on the Performance of Microfinance Institutions in Mezam. J. Finance Account. 2025, 13(3), 95-108. doi: 10.11648/j.jfa.20251303.12

    Copy | Download

    AMA Style

    Ngum ND. An Assessment of the Influence of Forensic Accounting on the Performance of Microfinance Institutions in Mezam. J Finance Account. 2025;13(3):95-108. doi: 10.11648/j.jfa.20251303.12

    Copy | Download

  • @article{10.11648/j.jfa.20251303.12,
      author = {Ngong Derick Ngum},
      title = {An Assessment of the Influence of Forensic Accounting on the Performance of Microfinance Institutions in Mezam
    },
      journal = {Journal of Finance and Accounting},
      volume = {13},
      number = {3},
      pages = {95-108},
      doi = {10.11648/j.jfa.20251303.12},
      url = {https://doi.org/10.11648/j.jfa.20251303.12},
      eprint = {https://article.sciencepublishinggroup.com/pdf/10.11648.j.jfa.20251303.12},
      abstract = {The rise in corporate crime and presence of fraudulent activities has led to the collapse of highly reputable MFIs in Cameroon. It is in this light that this current study was aimed at assessing the influence of forensic accounting on the performance of MFIs in Mezam. Two specific research questions and hypothesis were formulated to guide the study. The population of the study was made up of 490 employees of MFIs from which a sample of 220 employees was drawn using Loren’s formula and questionnaires administered. The questionnaires were analyzed using SPSS version 23 and SMART PLS package programs. The Specifically the findings show that a unit increase in the construct forensic audit results to 0.307 units increase in the overall performance of the MFI while a unit increase in the construct forensic litigation results to 0.121 units increase in the performance construct. Also, a unit increase in forensic audit will results to 0.469 units increase in forensic litigations. To conclude from the t-statistics the results revealed that both forensic audit and forensic litigation positively affect performance of MFIs but the effect of forensic litigation was positive and insignificant. At the end it was recommended that MFIs should employ the services forensic accountant on their activities, also they should adopt code of conduct governing the practice of forensic accounting. Last but not the least stake holders, authorities or government should impose the use forensic accounting and auditing in every organisation and other agencies to deter corruption in all sectors of the economy.
    },
     year = {2025}
    }
    

    Copy | Download

  • TY  - JOUR
    T1  - An Assessment of the Influence of Forensic Accounting on the Performance of Microfinance Institutions in Mezam
    
    AU  - Ngong Derick Ngum
    Y1  - 2025/06/11
    PY  - 2025
    N1  - https://doi.org/10.11648/j.jfa.20251303.12
    DO  - 10.11648/j.jfa.20251303.12
    T2  - Journal of Finance and Accounting
    JF  - Journal of Finance and Accounting
    JO  - Journal of Finance and Accounting
    SP  - 95
    EP  - 108
    PB  - Science Publishing Group
    SN  - 2330-7323
    UR  - https://doi.org/10.11648/j.jfa.20251303.12
    AB  - The rise in corporate crime and presence of fraudulent activities has led to the collapse of highly reputable MFIs in Cameroon. It is in this light that this current study was aimed at assessing the influence of forensic accounting on the performance of MFIs in Mezam. Two specific research questions and hypothesis were formulated to guide the study. The population of the study was made up of 490 employees of MFIs from which a sample of 220 employees was drawn using Loren’s formula and questionnaires administered. The questionnaires were analyzed using SPSS version 23 and SMART PLS package programs. The Specifically the findings show that a unit increase in the construct forensic audit results to 0.307 units increase in the overall performance of the MFI while a unit increase in the construct forensic litigation results to 0.121 units increase in the performance construct. Also, a unit increase in forensic audit will results to 0.469 units increase in forensic litigations. To conclude from the t-statistics the results revealed that both forensic audit and forensic litigation positively affect performance of MFIs but the effect of forensic litigation was positive and insignificant. At the end it was recommended that MFIs should employ the services forensic accountant on their activities, also they should adopt code of conduct governing the practice of forensic accounting. Last but not the least stake holders, authorities or government should impose the use forensic accounting and auditing in every organisation and other agencies to deter corruption in all sectors of the economy.
    
    VL  - 13
    IS  - 3
    ER  - 

    Copy | Download

Author Information
  • Department of Banking and Finance, Faculty of Economics and Management Sciences, The University of Bamenda, Bamenda, Cameroon
  • Abstract
  • Keywords
  • Document Sections

    1. 1. Introduction
    2. 2. Literature Review
    3. 3. Methodology
    4. 4. Results and Discussion of Finding
    5. 5. Conclusions and Recommendation
    Show Full Outline
  • Abbreviations
  • Declaration
  • Author Contributions
  • Conflicts of Interest
  • References
  • Cite This Article
  • Author Information